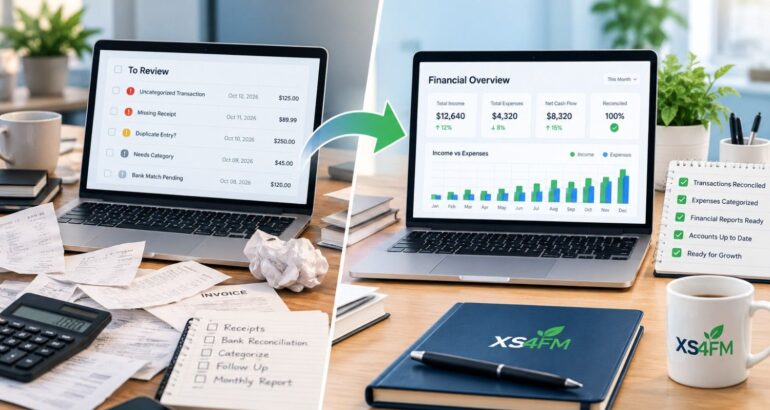
Most bookkeeping mistakes don’t come from carelessness. They come from a busy owner putting off a task that never feels urgent, until a lender, a tax deadline, or a confusing bank balance makes it urgent.
The good news: nearly every common error is fixable, and most are preventable with a simple routine. Below are seven of the most frequent bookkeeping mistakes small businesses make, what each one costs you, and how to fix it. If you want the full monthly routine, see our monthly bookkeeping checklist.
A quick note: bookkeeping is recordkeeping, not tax, legal, or audit advice. Talk to a qualified professional about your specific situation.
Quick Reference: Common Bookkeeping Mistakes and Fixes
| Mistake | Warning sign | Core fix |
|---|---|---|
| Uncategorized transactions | A growing “uncategorized” or “other” balance | Categorize weekly using consistent rules |
| Missed reconciliations | Book balance doesn’t match the bank | Reconcile every month, oldest month first |
| Mixing personal and business spending | Personal purchases on business cards | Separate accounts; document owner transfers |
| Inaccurate or incomplete records | Duplicates, missing receipts, wrong amounts | Capture documents at the source and review monthly |
| Delayed financial reporting | Reports arrive months late | Close each month on a set schedule |
| Ignoring unpaid invoices and bills | Surprise cash shortfalls | Review receivables and payables monthly |
| Judging profit by bank balance | Cash looks fine but profit is unclear | Read the profit and loss statement |
7 Common Bookkeeping Mistakes (and How to Fix Each One)
1. Leaving Transactions Uncategorized
What happens: Income and expenses pile up in a catch-all category, so your reports can’t tell you where money is actually going.
Why it matters: A profit and loss statement is only as useful as the categories behind it. Uncategorized transactions also make it harder to spot errors and prepare for tax time.
How to fix it:
- Set aside a short weekly block to categorize new transactions.
- Create rules in your accounting software for recurring vendors.
- Keep a simple chart of accounts, and avoid adding new categories for one-off items.
- Track down the receipt or invoice for anything you can’t identify.
2. Skipping or Delaying Reconciliations
What happens: Your books and your bank or credit card statements stop matching, and nobody notices.
Why it matters: Bank reconciliation is how you catch missing entries, duplicates, wrong amounts, and unfamiliar charges. The longer you wait, the harder each difference is to trace.
How to fix it:
- Reconcile every account monthly when statements arrive.
- If you’re behind, start with the oldest unreconciled month and work forward.
- Investigate every difference rather than adjusting it away.
- Record credit card payments as payments, not as new expenses, to avoid double-counting.
3. Mixing Personal and Business Expenses
What happens: Groceries, personal subscriptions, or family travel run through the business account, or business costs go on a personal card.
Why it matters: Mixed transactions make your records harder to interpret and defend, and they distort your reports. They can also raise questions about the separation between you and your business, so ask a tax professional or attorney how this applies to your structure.
How to fix it:
- Open a dedicated business bank account and, if appropriate, a business credit card.
- Pay yourself through owner draws or payroll, depending on your structure, rather than ad hoc transfers.
- Record money you put in or take out as owner contributions or withdrawals.
- Move past personal items into the correct owner-related accounts, with notes, instead of leaving them as business expenses.
New business? Our guide to bookkeeping for startups covers setting this up in year one.
4. Keeping Inaccurate or Incomplete Records
What happens: Receipts get lost, entries are duplicated, amounts are mistyped, or invoices never get recorded.
Why it matters: Small errors compound. Inaccurate records lead to unreliable reports, and missing documentation makes it harder to support your numbers later.
How to fix it:
- Capture receipts the day you get them, using a phone photo or an app that attaches to transactions.
- Store invoices and bills in one organized place, labeled by month.
- Use bank feeds instead of manual entry where possible, and review imported transactions for duplicates.
- Do a monthly review of unusual amounts and missing documents.
5. Delaying Financial Reporting
What happens: You only look at your numbers at tax time, or months after the fact.
Why it matters: Reports that arrive late can’t guide decisions. You may miss a cost trend or cash shortfall until it’s hard to respond.
How to fix it:
- Set a monthly close date, such as the 10th, and stick to it.
- Review your profit and loss statement, balance sheet, and cash flow report each month.
- Look for categories that jumped and balances that don’t look right.
6. Ignoring Unpaid Invoices and Bills
What happens: Customer invoices go unpaid without follow-up, and vendor bills slip past their due dates.
Why it matters: Receivables you don’t chase can strain cash flow, and missed payables can lead to late fees. Both distort your picture of what you really have.
How to fix it:
- Review an accounts receivable aging report monthly and follow up on late payments.
- Record bills when they arrive and track due dates.
- Plan upcoming payments around expected cash.
7. Judging Profit by the Bank Balance
What happens: A healthy balance makes the business feel profitable, or a low one makes it feel like a failure.
Why it matters: A bank balance ignores unpaid bills, money owed by customers, and timing. It shows cash, not profit.
How to fix it:
- Use the profit and loss statement to judge profitability.
- Use a cash flow report to understand timing.
- Compare both against your budget, if you have one.
How to Fix Bookkeeping Mistakes That Have Already Piled Up
If you recognize several of these problems, resist the urge to start fresh this month. Old gaps carry forward and distort every report that follows. Work through the backlog in order:
- Gather statements and documents for every month you’re missing.
- List what’s missing, such as unrecorded months, lost receipts, or unexplained transactions.
- Check your opening balances so your starting point is correct.
- Categorize past transactions, oldest first.
- Reconcile each account, investigating every difference.
- Review your reports for anything that still looks off.
- Move to a monthly routine so the problem doesn’t return.
If the backlog is large, it can help to bring in support. XS4FM’s catch-up bookkeeping services are designed for organizing and reconciling overdue records, and our article on catch-up bookkeeping vs. regular bookkeeping explains how cleanup and ongoing work differ.
How to Prevent Bookkeeping Mistakes Going Forward
A few habits prevent most of the problems above:
- Separate business and personal money from day one.
- Categorize weekly, reconcile monthly, and close the month on a set date.
- Capture documents at the source, not at year-end.
- Review reports every month, not just at tax time.
- Keep notes on unusual transactions and adjustments so future you understands them.
When to Consider Professional Bookkeeping Help
Many owners handle their own books well at first. It may be time for help if you’re spending too much time on bookkeeping, reconciliations keep slipping, reports are inconsistent, or the business is growing faster than your records. Bookkeeping services for small businesses can take the recurring work off your plate and keep your records current. The right level of help depends on your transaction volume, complexity, and budget.
Frequently Asked Questions
What are the most common bookkeeping mistakes?
The most common are leaving transactions uncategorized, skipping bank reconciliations, mixing personal and business expenses, keeping incomplete records, and delaying financial reports. Ignoring unpaid invoices and relying on the bank balance to gauge profit are also frequent.
How do I fix bookkeeping errors?
Start by gathering statements and documents, then correct entries in order, oldest first. Categorize transactions, reconcile each account, and investigate differences instead of forcing them to match. Once records are current, adopt a monthly routine to prevent new errors.
How often should I reconcile my accounts?
At least monthly, when statements arrive. Businesses with high transaction volume may reconcile weekly. Regular reconciliation catches missing entries, duplicates, and unfamiliar charges while the details are still easy to trace.
Can bookkeeping mistakes cause problems at tax time?
They can make preparation harder, since your tax professional needs accurate, categorized records. Missing documentation and unreconciled accounts can slow things down. Ask a qualified tax professional how your records affect your specific filings.
Is it okay to catch up on bookkeeping months later?
Yes. Many businesses do. The key is to work through the backlog methodically, reconciling each account, before starting a regular monthly routine. A professional catch-up service can speed this up if the backlog is large.
When should I hire a bookkeeper?
Consider it when bookkeeping takes too much of your time, accounts go unreconciled, reports are late or unreliable, or transaction volume is growing. The right timing depends on your complexity, budget, and comfort managing the books yourself.
Fix Today’s Bookkeeping Mistakes Before They Become Bigger Problems
Bookkeeping mistakes are common, fixable, and mostly preventable. Pick the one that affects you most, whether that’s uncategorized transactions, a missed reconciliation, or late reports, and start there. A consistent monthly routine does the rest.
If you’d like help, contact XS4FM to discuss your bookkeeping needs, or learn more about XS4FM and its financial management services.
