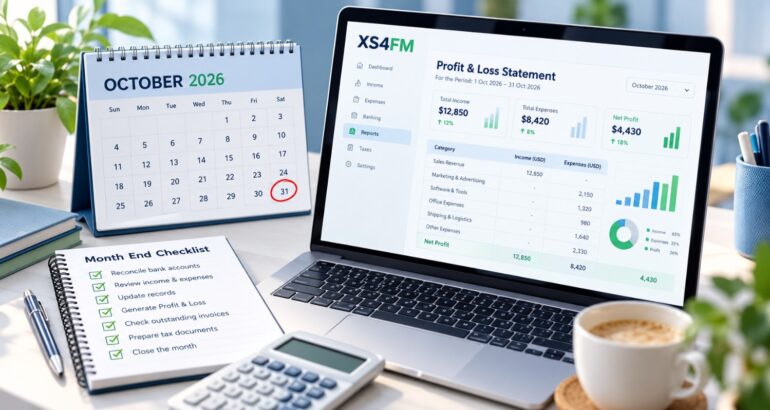
A monthly bookkeeping checklist is a repeatable list of tasks you complete at the end of every month to keep your financial records accurate, current, and ready to use. For most small businesses, that means collecting documents, categorizing transactions, reconciling accounts, following up on invoices and bills, and reviewing your financial reports.
Doing this consistently matters. Monthly bookkeeping helps you spot missing transactions while they’re easy to trace, see where cash is going, and avoid the stress of untangling a year of records at once. The checklist below is written for owners without an accounting background, so each step explains what to do and why it matters.
A quick note: bookkeeping is recordkeeping, not tax, legal, or audit advice. Your obligations depend on your business structure, location, and circumstances, so check with a qualified tax professional for specifics.
Why Monthly Bookkeeping Is Important
Books that are updated monthly give you a reliable picture of your business while there is still time to act on it. Here is what you gain:
- Accurate financial records. Errors and duplicates are far easier to fix a few weeks after they happen.
- Better cash flow visibility. You can see what is coming in, what is going out, and where timing gaps may appear.
- A clearer view of profitability. Your bank balance alone doesn’t show whether the business is making money.
- Faster detection of unusual transactions. Unfamiliar charges stand out when you review activity regularly.
- More organized year-end tax preparation. Your tax preparer receives clean, categorized records instead of a shoebox of receipts.
- Better-informed decisions. Pricing, hiring, and spending choices are stronger when they rest on current numbers.
The Monthly Bookkeeping Checklist
Work through these twelve tasks in order each month. Some will take minutes; others take longer depending on your transaction volume and how complex your business is.
1. Collect and Organize Financial Documents
Gather everything that supports your transactions: bank and credit card statements, receipts, vendor bills, customer invoices, and payment processor reports from platforms like Stripe, PayPal, or Square. Store them in a consistent folder structure, either digital or paper, labeled by month. Having documents in one place makes every later step faster.
2. Record All Business Income and Expenses
Enter every transaction into your accounting software and assign it to the right income or expense category. This is called transaction categorization. Look for missing entries, duplicates, and anything you can’t identify, and track down the supporting document before moving on. Keep personal spending out of the business books entirely.
3. Reconcile Business Bank Accounts
Bank reconciliation means matching the transactions in your books against your bank statement so the ending balances agree. Investigate any difference, such as a missing deposit, a duplicate entry, or a transaction recorded in the wrong amount. Reconciling every month keeps small discrepancies from becoming large ones.
4. Reconcile Business Credit Cards
Credit card reconciliation works the same way. Compare each statement with your recorded transactions, confirm the totals match, and look closely for duplicate or unfamiliar charges. Check that card payments are recorded as payments rather than expenses, so you don’t count the same spending twice.
5. Review Accounts Receivable
Accounts receivable is money customers owe you. Run an aging report to see which invoices are unpaid and how overdue they are. Follow up on late balances promptly, and note any invoices you may need to adjust or write off. Strong receivables follow-up supports healthier cash flow management.
6. Review Accounts Payable
Accounts payable is money you owe vendors. Confirm that every bill you received is recorded, check due dates, and plan upcoming payments around your available cash. This helps you avoid late fees and keeps vendor relationships in good standing.
7. Review Payroll and Related Records
If you have employees, review your payroll reports each month, along with related liabilities and the payments made for them. Confirm that wages, withholdings, and payments match your books. Requirements vary by business, state, and payroll setup, so confirm the details with your payroll provider or tax professional.
8. Review Loan Payments, Interest, and Other Liabilities
Check that loan balances in your books match your lender statements, and that principal and interest are recorded correctly. Review recurring subscriptions and other commitments too, so you can cancel anything you no longer use and keep obligations visible.
9. Review Inventory and Cost of Goods Sold Where Applicable
If you sell physical products, your inventory purchases and cost of goods sold affect how profitable each sale really is. Compare inventory records to what you actually have on hand, review purchases for the month, and check that costs are recorded in the right period. Service businesses can usually skip this step.
10. Review Financial Statements
Once transactions are recorded and reconciled, your monthly financial statements are ready for review:
- Profit and loss statement: shows revenue and expenses for the month. Look for categories that changed sharply or amounts that don’t look right.
- Balance sheet: shows what you own, what you owe, and your equity on a given date. Check that bank, receivable, and payable balances match what you expect.
- Cash flow report: shows how cash moved in and out. Compare it with your bank activity to see where cash went.
The goal is to spot errors and unusual changes, not to draw conclusions on its own. If something looks off, investigate before relying on the numbers.
11. Review Budget Versus Actual Performance
If you use a budget, compare actual revenue and expenses with your plan. Investigate meaningful variances: was a cost one-time, a pricing change, or a categorization error? Over several months, this comparison shows you where your assumptions need adjusting.
12. Back Up Records and Close the Month
File supporting documents, document any adjusting entries, and back up your accounting data. Then finalize the month so that prior periods aren’t changed accidentally. Retention periods differ by record type; as general IRS guidance, records supporting items on a tax return are typically kept for at least three years, and employment tax records for at least four, with longer periods in some situations. Confirm your own requirements with a tax professional.
Monthly Bookkeeping Checklist at a Glance
Print this table or copy it into your task manager and check off each item monthly.
| Task | What to Check | Completed |
|---|---|---|
| 1. Collect documents | Bank and card statements, receipts, bills, invoices, processor reports | ☐ |
| 2. Record income and expenses | All transactions entered, categorized, no duplicates or gaps | ☐ |
| 3. Reconcile bank accounts | Book balance matches statement; differences resolved | ☐ |
| 4. Reconcile credit cards | Statement totals match; no unfamiliar charges | ☐ |
| 5. Review receivables | Unpaid and overdue invoices; follow-ups sent | ☐ |
| 6. Review payables | Bills recorded; due dates and payment plan confirmed | ☐ |
| 7. Review payroll | Payroll reports, liabilities, and payments agree with books | ☐ |
| 8. Review loans and liabilities | Balances, interest, and recurring subscriptions | ☐ |
| 9. Review inventory and COGS | Counts, purchases, and costs (if you sell products) | ☐ |
| 10. Review financial statements | Profit and loss, balance sheet, cash flow report | ☐ |
| 11. Review budget vs. actual | Major variances explained | ☐ |
| 12. Back up and close | Documents filed, adjustments noted, books closed | ☐ |
Common Monthly Bookkeeping Mistakes to Avoid
Even careful owners fall into these traps:
- Mixing personal and business transactions. It muddies your reports and makes records harder to defend.
- Leaving transactions uncategorized. Reports are only as useful as the categories behind them.
- Skipping bank reconciliation. Without it, errors can sit unnoticed for months.
- Ignoring overdue invoices. Late receivables strain cash flow.
- Missing business expenses. Unrecorded expenses understate costs and can cause you to overlook deductions you may be entitled to; ask your tax professional what applies.
- Delaying bookkeeping for several months. Details fade, and cleanup takes longer.
- Relying only on bank balances to judge profitability. Balances ignore unpaid bills, receivables, and timing.
- Failing to retain supporting documentation. You may need receipts and statements to support your records later.
What If Your Bookkeeping Is Already Several Months Behind?
Routine monthly bookkeeping keeps current records up to date. Catch-up or cleanup bookkeeping is different: it organizes and reconciles past months so your records are reliable again before you resume a normal routine.
Common warning signs include:
- Bank or credit card accounts that haven’t been reconciled for months
- Missing or uncategorized transactions
- Reports that don’t match your bank balances
- Reluctance to open your accounting file because you know what you’ll find
If you recognize these signs, resist the urge to simply start fresh this month. Old gaps carry forward and distort your current reports. Many businesses benefit from reconciling historical records first. If that sounds like your situation, catch-up bookkeeping services can help you get overdue bookkeeping records organized so you can start your monthly routine from a clean baseline.
When Should a Small Business Consider Professional Bookkeeping Services?
Many owners manage their own books well in the early days. Outsourcing may be worth exploring when:
- You have limited time to keep up with bookkeeping internally
- Transaction volume is increasing
- You struggle to reconcile accounts
- Monthly reporting is inconsistent or late
- You want a more organized, repeatable process
- Growth is making your financial records more complex
Outsourced bookkeeping services can bring consistency to the checklist above, with someone responsible for completing it on schedule. If you’re weighing your options, learn more about bookkeeping services for small businesses and what ongoing monthly support can look like. Whatever you choose, ask what’s included, how often you’ll receive reports, and how your financial data is protected.
Frequently Asked Questions
What should be included in a monthly bookkeeping checklist?
A solid checklist covers document collection, transaction recording and categorization, bank and credit card reconciliation, accounts receivable and payable review, payroll and liability checks, financial statement review, and closing the month. Add inventory and budget comparisons if they apply to your business.
How often should a small business reconcile its bank accounts?
At minimum, monthly, when your statement arrives. Businesses with high transaction volume may reconcile more often, such as weekly, so issues surface sooner.
How long does monthly bookkeeping take?
It depends on transaction volume, the number of accounts, and how current your records already are. A small business with few transactions may need a few hours; a busier or more complex one may need considerably more.
What financial reports should a small business review each month?
Most owners review a profit and loss statement, a balance sheet, and a cash flow report. Accounts receivable and payable aging reports are also useful for tracking unpaid invoices and bills.
Can a small business outsource monthly bookkeeping?
Yes. Many businesses outsource monthly bookkeeping to online or remote providers. Scope, pricing, and reporting schedules vary, so compare providers against the tasks you need done.
What should a business do if its bookkeeping is several months behind?
Start by gathering statements and documents for the missed months, then reconcile accounts and categorize transactions in order, oldest first. If the backlog is large, a catch-up bookkeeping provider can help. Once records are current, move to a monthly routine.
Make Monthly Bookkeeping Easier With a Consistent Process
A monthly bookkeeping checklist turns a vague chore into a routine you can finish. Set a recurring date, work through the steps, and keep your documents organized as you go. Consistency catches problems early, keeps your reports trustworthy, and makes tax season less stressful.
If maintaining the routine becomes difficult, that’s a good time to seek professional help.
Ready to get your business finances organized? Explore XS4FM’s bookkeeping and financial services to learn more about how XS4FM supports small business finances.